
After the November 5 sell-off, the tech-heavy index enters correction territory as concerns grow over investment, regulation
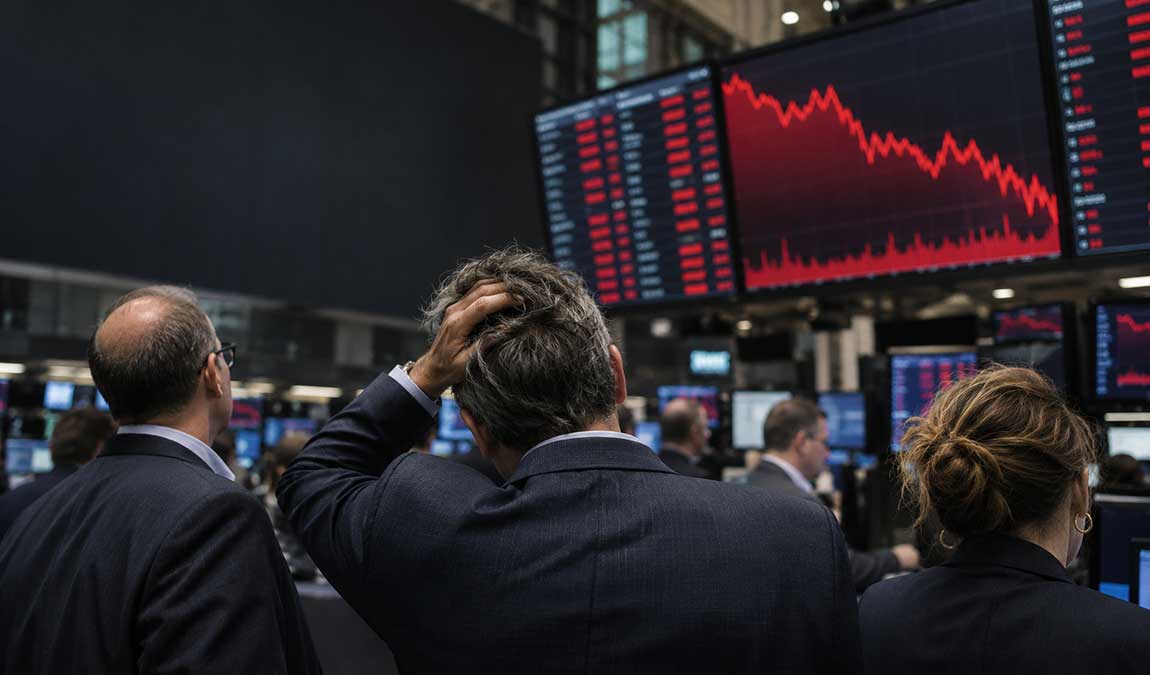
The Nasdaq Composite fell 5.52% on Thursday, November 5, closing at 24,315 points—down 1,421.52 points from the previous session. It was the index’s steepest daily decline since April 2025 and left it about 11.9% below its October 6 closing high, putting it in correction territory under the commonly used definition: a fall of at least 10% from a recent peak. Other indexes also dropped: the S&P 500 fell 4.4% and the Dow Jones 3.4%.
The sell-off did not come out of nowhere: the Nasdaq had been under pressure for weeks. Selling was concentrated in semiconductors, artificial intelligence infrastructure companies and data center operators. The Philadelphia Semiconductor Index fell about 12%; Nvidia lost 9%, while AMD dropped 17%.
Why investors sold
The political trigger came from the results of the U.S. midterm elections. The Democrats’ victory in Congress fueled concerns about tighter oversight and obstacles to data center projects, particularly in areas where energy consumption, water use and pressure on power grids are already contentious issues. Investors reassessed how quickly the infrastructure needed for AI can expand.
But the issue goes beyond politics. Major companies are committing large sums to chips, servers and data centers, while investors and analysts want clearer evidence that these investments will translate into revenue and profits. Debt financing and the still-high cost of capital make the outlook more precarious for companies that need to raise funds to build future capacity. Results and guidance from some technology companies have also failed to dispel doubts about returns on investment. In short, the market is shifting from enthusiasm about AI’s potential to scrutiny of its costs and profitability.
The concentration of the index in technology stocks and rising volatility intensified the correction. When positions are crowded and valuations are high, a change in expectations can trigger widespread selling. The jump in volatility and steep losses across companies tied to the same investment cycle drove a repricing that spread to the broader market.
Historical comparisons: similar scale, different causes
A 5.5% decline is extreme compared with a typical market session, but it does not rank among the Nasdaq Composite’s worst days. The comparison helps distinguish a sharp one-day drop from a systemic crash:
| Date | Nasdaq Composite change | Context |
|---|---|---|
| October 19, 1987 | −11.35% | “Black Monday”: a global market crash amplified by automated selling and market tensions. |
| April 14, 2000 | −9.67% | Dot-com bubble burst: technology valuations plunged and confidence in the sector deteriorated rapidly. |
| September 29, 2008 | −9.14% | Global financial crisis, after the first vote on the U.S. bailout plan failed. |
| March 12, 2020 | −9.43% | Pandemic shock, lockdowns and fears for the global economy. |
| March 16, 2020 | −12.32% | The most acute phase of selling during the Covid crisis. |
| November 5, 2026 | −5.52% | Concerns about AI spending, data center regulation and the sustainability of financing. |
The most severe declines came when markets faced systemic shocks or a profound reassessment of valuations: the 1987 crash, the dot-com bubble, the 2008 financial crisis and the pandemic. Yesterday’s session was intense, but its immediate cause was more narrowly focused: a reassessment of risk and expected returns in the AI sector, with consequences for the broader tech market. That does not rule out a deeper correction if concerns spread to earnings, credit or economic growth.
The coming weeks: volatility and a test of fundamentals
Wide swings are likely in the near term. Thursday’s sell-off suggests investors have become more selective, and news about permits, financing or corporate spending plans could move stocks quickly. The Nasdaq’s correction alone, however, cannot tell us whether the decline is nearing its end or is the start of a deeper fall.
A stabilization scenario would become more credible if companies continued to confirm demand and AI-related revenue, investment plans remained financeable, and pressure from interest rates eased. By contrast, delays to data center projects, further cuts to company outlooks or signs of tighter credit could prompt investors to reduce exposure further to stocks whose valuations depend heavily on future growth.
The cautious view for the coming weeks is therefore high volatility, with the direction still uncertain. The correction may remain limited or turn into a broader decline; the next signals will come chiefly from earnings, capital spending, interest rates and approvals for infrastructure projects. Past performance does not determine future results. This is a scenario, not a certain forecast or personalized investment advice.
© 4FT Invest LTD. All rights reserved
